Business Loan Vs Business Credit Line: Which Is Better for Your Business
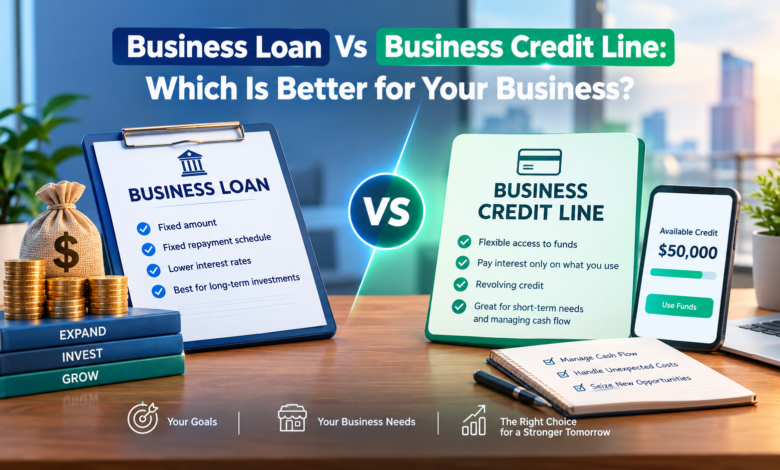
All businesses need financing at the right time. Financing can be required to buy new equipment, establish another business center, prepare for peak season, or even to give employees salary when waiting for a client to clear the invoices. Choosing which type of finance to use is quite difficult at first, but most business people always choose from two known forms of business financing: term loan and line of credit.
The difference is basic. With a loan, you will receive a single amount and repay it in equal amounts. With a line of credit, however, you will have access to a specified amount of money that you will borrow when necessary. Depending on your purpose, the amount of money you can afford to repay, and your long term goals, either one can work best for you.
What Is a Business Loan?
A business loan refers to a certain amount of money provided to you in full. This loan is repaid, along with the interest, after a certain period of time in installments.
There are different types of business loans including:
- Term loan: Certain amount that will be paid back in one to few years.
- Equipment loan: Loan obtained for purchasing equipment and/or vehicles.
- Working capital loan: Loan borrowed for operating your business on a day-to-day basis.
- Guaranteed loans: Guaranteed by government and designed to support small businesses.
A small business loan will suit you well if you know precisely how much money you need and for what purpose.
What Is a Business Line of Credit?
An overdraft facility means that you can borrow at any time up to a particular limit as approved by the lending institution.
It is explained below:
- You can borrow whenever the need arises.
- The interest rate will be charged on the actual amount borrowed and not the entire limit.
- Every time you pay back the loaned amount, you gain access to your overdraft facility again.
In case your limit is ₹10 lakh, and you borrow ₹3 lakh, the remaining amount of ₹7 lakh is still available to you. Once you have paid back the ₹3 lakh amount borrowed, the total amount of ₹10 lakh will become available to you.
Business Loan vs. Business Credit Line: Key Differences
When comparing a business loan vs line of credit, the table below shows how the two differ at a glance.
| Feature | Term Loan | Credit Line |
| Funding structure | One lump sum paid upfront | Revolving access up to an approved limit |
| Interest and fees | Interest on the full amount; may include processing fees | Interest only on the amount used; may include draw or maintenance fees |
| Repayment terms | Fixed installments over a set period | Flexible; minimum payments on the balance used |
| Borrowing flexibility | Low; new funds need a new application | High; borrow, repay, and borrow again |
| Approval requirements | Often requires strong credit, financials, and sometimes collateral | Often requires steady revenue and good credit; limits may be reviewed regularly |
| Best use cases | Equipment, expansion, large one-time projects | Inventory, payroll, seasonal or unexpected costs |
What Are the Benefits of Each Financing Option?
Benefits of a Business Loan
- Best suited for planned and big expenses: When you know your expenditure and its purpose, then this is the best type of loan for you.
- Fixed payments: The installment will be fixed, so it will be easy for you to manage your payments.
- Longer repayment period: You can have up to several years to pay off the loan
Benefits of a Business Line of Credit
- Borrow as much as required: You will not have to pay interest on money that is lying idle.
- Recyclable money: The repayments reset your limit according to the agreement.
- Money flow support: This helps fill temporary gaps, like awaiting customer payments.
When Should You Choose a Business Loan or Credit Line?
Term loans are preferred when you make your investment just one time: buy the equipment, expand, start a new product line, etc. You know the exact sum and are ready to work out the payment schedule. Credit line works better if your expenses are fluctuating each month. Seasonal companies, companies whose demands for inventory fluctuate from month to month, and companies that want some margin of safety will benefit from this product the most.
The combination of these two products may also be very effective. Companies get the loan for their long-term investments and keep the credit line for their working capital. For example, the restaurant receives the loan for the kitchen remodeling and keeps the credit line to deal with the suppliers during slow months.
How Can You Qualify for Business Financing?
The lender will need to be assured that you are capable of repaying them. The following information is usually looked into by lenders:
- Credit score: This involves both the business and the personal credit score.
- Earnings: Earning capability proves repayment capability.
- Length of time in business: A business operating for at least one to two years is preferred.
- Cash Flow: This implies adequate cash flow for making regular payments.
- Financial Documentation: This entails bank statements, tax returns, record of income and expenses, and balance sheets.
- Collateral or personal guarantee: Collateral or some personal guarantee may be required by some lenders.
Conclusion
Term Loan is used for funding of investment activities in predetermined sums which can be paid back in a foreseeable manner. The Line of Credit lets you borrow money for your short-term needs in flexible amounts. Neither instrument is intrinsically better than the other.
Ponder over your decision since there are many aspects to be taken into account while comparing different lenders in terms of their eligibility criteria, payment options, fees, and overall cost of borrowing. Your decision will depend upon the reason for borrowing the money.